Toyota Corolla Leasing Deals: How to Get the Best Monthly Price in 2026
Toyota Corolla leasing deals are one of the cheapest ways to drive a brand-new Corolla without paying the full purchase price, because a lease only charges you for the value the car loses during the contract rather than the whole cost of the vehicle. A typical Toyota Corolla lease runs for 24 to 48 months, asks for an initial payment and a fixed monthly rental, and ends with you handing the car back, so you can move into a newer model without worrying about selling or trading in an older one. The Corolla suits this arrangement particularly well, since its strong resale value keeps monthly payments lower than many rivals, and its reputation for reliability means you are unlikely to face expensive surprises during the term.
Before you compare any Toyota Corolla leasing deals, it helps to know exactly what you are looking at, because advertised monthly prices only make sense once you understand the term, the mileage allowance, the amount due at signing and the fees hiding in the small print. A headline figure of under two hundred dollars or pounds a month can look irresistible, yet the same offer may demand several thousand upfront, limit you to ten thousand miles a year, and add a disposition fee when the car goes back. This guide explains how Corolla leasing works, what shapes the monthly cost, which trims make the best lease candidates, and the checks that separate a genuinely good deal from a tempting headline.
How Does Toyota Corolla Leasing Work?
Leasing a Toyota Corolla means you pay to use the car for an agreed period, usually two to four years, while the leasing company or finance provider remains the legal owner throughout the contract. Your monthly payment covers the difference between the car’s price when new and its predicted value at the end of the term, which is known as the residual value, plus interest or a rent charge and any fees. Because the Corolla holds its value better than most compact cars, the gap between its new price and its residual value is relatively small, and that is the main reason Toyota Corolla leasing deals often look so affordable next to larger or faster-depreciating rivals.
At the end of the agreement you normally have three choices, which are to return the car and walk away, to lease a brand-new Corolla and start a fresh contract, or to buy the car outright for the agreed residual value if your contract allows it. Most personal leases in the United Kingdom are personal contract hire agreements, where you never own the car and simply return it, while in the United States closed-end leases work in a similar way through Toyota Financial Services or a bank. You are responsible for keeping the car serviced, insured and in good condition, and you must stay within the agreed annual mileage, because excess miles and damage beyond fair wear and tear are charged when the vehicle is returned.
Which Toyota Corolla Trim Leases Best?
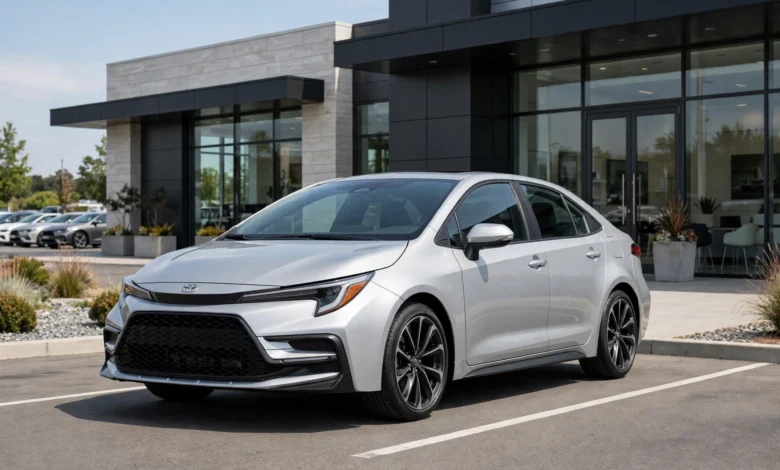
The 2026 Toyota Corolla sedan is sold in the United States in three petrol trims called LE, SE and XSE, and every one of them uses the same 2.0-litre Dynamic Force four-cylinder engine producing 169 horsepower and 151 lb-ft of torque through a continuously variable transmission with front-wheel drive. The LE is the efficiency leader of the petrol range with an EPA-estimated 35 miles per gallon combined, while the sportier SE and XSE return an EPA-estimated 34 miles per gallon combined, so fuel costs barely differ between trims and the choice comes down to equipment. The LE gives you the lowest monthly payment, the SE adds larger wheels and sportier styling, and the XSE adds a power moonroof, heated seats and a larger digital gauge cluster for drivers who want more comfort.
There is also a hybrid version of the 2026 Corolla, offered in LE, SE and XLE trims, which pairs a 1.8-litre four-cylinder engine with Toyota’s hybrid system for a combined 138 horsepower and an EPA-estimated fuel economy of up to 50 miles per gallon combined on the front-wheel-drive Hybrid LE and XLE. Hybrid trims usually cost more to lease each month because their starting price is higher, yet drivers who cover big annual mileages can claw some of that back through lower fuel bills over the term. Every 2026 Corolla trim, petrol or hybrid, comes standard with Toyota Safety Sense 3.0, an advanced suite of driver assistance technology, and every new Toyota includes ToyotaCare, which covers normal factory scheduled maintenance for one year or ten thousand miles together with 24-hour roadside assistance.
What Affects Your Monthly Toyota Corolla Lease Payment?
The single biggest influence on your monthly payment is the price you negotiate for the car, because even a lease payment is calculated from the selling price, so a discount off the manufacturer’s suggested retail price flows straight into a lower rental. The second major factor is the residual value, which is the finance company’s forecast of what the car will be worth when the contract ends, and the Corolla’s strong resale record works in your favour here. The money factor, which is the leasing equivalent of an interest rate, depends on your credit score and on the finance programme available at the time, so a stronger credit profile generally earns a cheaper deal, and manufacturer-backed incentives can reduce the money factor further during promotional periods.
Your choices about the contract itself matter just as much, because a longer term usually lowers the monthly figure while raising the total amount you pay, and a bigger initial payment cuts the monthly rental at the cost of more cash upfront. Annual mileage is another lever, since a ten-thousand-mile-a-year allowance is cheaper than twelve or fifteen thousand miles, but choosing too few miles is a false economy when excess mileage is charged at rates such as fifteen cents per mile in the United States. Optional extras, paint choices and dealer-fitted accessories also push the price up, so the smartest way to keep Corolla lease costs affordable is to pick a modest trim, agree a realistic mileage allowance, and compare the total cost of the whole contract rather than the monthly figure alone.
What Should You Check Before Signing a Corolla Lease?
Always read the total cost of the lease before you sign anything, because the monthly payment is only one part of the bill and the amount due at signing, the acquisition fee, the disposition fee at the end of the contract, and any dealer charges can add thousands to the real price. In the United States, advertised Toyota offers have recently included an acquisition fee of 750 dollars and a disposition fee of 350 dollars, so those two items alone are worth checking on any quote you receive. You should also confirm whether the quoted payment includes tax, because advertised prices in the United States usually exclude taxes and government fees, while prices quoted by United Kingdom brokers usually include VAT for personal customers and exclude it for business customers.
Check the mileage allowance against your real driving habits, and ask what each extra mile will cost before you commit, because a driver who covers fifteen thousand miles a year on a ten-thousand-mile contract can face a painful bill at handback. Look closely at the wear and tear policy as well, since scuffed alloys, chipped paint and stained interiors can all attract charges, and consider gap insurance, which covers the difference between what your insurer pays and what you still owe if the car is written off. Finally, confirm the servicing requirements, because the lease will usually require the car to be maintained on schedule, and ask whether maintenance is included or charged separately, so you can budget for the full cost of running the car rather than just the monthly rental.
Are Advertised Toyota Corolla Leasing Deals Worth It?
Advertised offers can be genuinely good value, but only when they match your region, your mileage and your timing, because manufacturer lease programmes vary by area and change from month to month. As an example of how much the terms can vary, Toyota advertised a 2026 Corolla LE lease in the New York area at 279 dollars a month for 36 months with 279 dollars due at signing, based on ten thousand miles a year, with a 750-dollar acquisition fee and a 350-dollar disposition fee, and that particular offer expired on 2 November 2026 according to Toyota’s own offer page. A separate November 2026 advertised offer listed by Autofinder for the mid-Atlantic states quoted 199 dollars a month for 39 months with 3,999 dollars due at signing, again on ten thousand miles a year, running to 30 November 2026, which shows how the same car can carry a very different monthly figure once the upfront payment changes.
The lesson is that no single advertised price tells the whole story, and the fairest comparison is the total cost of the contract, which is the initial payment plus every monthly payment plus the fees you will pay at the end. In the United Kingdom, brokers listed Toyota Corolla hatchback hybrid examples from around 294 pounds a month including VAT in November 2026, with terms such as a 12-month initial rental and a 48-month contract, which again underlines that the headline figure depends heavily on the deposit and the term. Always get at least three written quotes for the same trim, term and mileage, check that each one is available in your area, and ask the dealer to confirm the offer in writing before you pay any deposit or arrange insurance.
Toyota Corolla Leasing Deals vs Buying: Which Wins?
Leasing wins when you want a new car every few years, low monthly payments, warranty cover for most of the time you drive the car, and no worry about what the car will be worth when you finish with it. A new Corolla carries a manufacturer warranty that covers most of the typical lease term, and because you return the car, you never face the hassle of selling privately or negotiating a trade-in value. For drivers who enjoy new technology and safety features, and who drive a predictable number of miles each year, Corolla leasing is often the simplest and cheapest route into a brand-new car.
Buying wins when you drive very high mileages, want to keep the car for many years, or prefer to own an asset that you can sell later, because a lease charges you for excess miles and gives you nothing to show for your payments at the end. A buyer who keeps a Corolla for eight or ten years will usually spend less overall than someone who leases two or three new cars in the same period, and an owner can modify the car, drive unlimited miles and sell it whenever they choose. The right choice therefore depends on your habits rather than on the car itself, so work out your annual mileage, how long you realistically keep a car, and whether you value ownership or flexibility more before you decide.
Conclusion
Toyota Corolla leasing deals are among the most affordable ways to drive a new car, thanks to the Corolla’s strong residual values, its efficient engines and its reputation for trouble-free motoring. The 2026 Corolla LE offers the lowest monthly cost with an EPA-estimated 35 miles per gallon combined, the SE and XSE add style and comfort for a modest premium, and the hybrid trims reward high-mileage drivers with fuel economy of up to 50 miles per gallon combined. Yet the headline monthly price is never the whole story, so compare the total cost of each contract, match the mileage allowance to your real driving, and check every fee before you sign. Do that, and a Corolla lease can be a genuinely smart, low-stress way to enjoy a brand-new car.
How much is a Toyota Corolla lease per month?
A Toyota Corolla lease payment depends on the trim, the term, the initial payment, the annual mileage and your location, so there is no single fixed monthly price that applies everywhere. As an example of the range, Toyota advertised a 2026 Corolla LE in the New York area at 279 dollars a month for 36 months with 279 dollars due at signing in late 2026, while a separate November 2026 advertised offer for the mid-Atlantic states quoted 199 dollars a month for 39 months with 3,999 dollars due at signing, both based on ten thousand miles a year. In the United Kingdom, brokers listed Corolla hatchback hybrid examples from around 294 pounds a month including VAT in November 2026. Always compare the total cost of the contract, not just the monthly figure, and confirm the offer is available in your area.
Can you lease a Toyota Corolla with no deposit?
Some Toyota Corolla leasing deals are advertised with no deposit or with only the first month’s payment due at signing, and Toyota itself has advertised offers with 279 dollars due at signing and no customer down payment on a 2026 Corolla LE. A no-deposit lease is convenient because it keeps your cash in the bank, but it almost always raises the monthly payment, since the amount you would have paid upfront is spread across the term instead. In the United Kingdom, personal contract hire usually asks for an initial rental equal to three, six, nine or twelve monthly payments, and a larger initial rental lowers the monthly figure. Ask for quotes with different initial payments so you can see the trade-off clearly before you choose.
How many miles can you drive on a Corolla lease?
Most Toyota Corolla leasing deals in the United States are based on ten thousand miles a year, although twelve thousand and fifteen thousand mile contracts are usually available for a higher monthly payment. In the United Kingdom, annual mileage allowances commonly range from five thousand to thirty thousand miles, and you choose the figure when the contract is set up. Driving beyond the agreed limit triggers excess mileage charges, which were fifteen cents per mile on the advertised 2026 Corolla lease offers in the United States, so it is cheaper to choose a realistic allowance at the start than to pay for extra miles at the end of the contract.
Is it better to lease or buy a Toyota Corolla?
Leasing a Toyota Corolla is usually better if you want low monthly payments, a new car every two to four years, and warranty cover for most of your driving, because you only pay for the value the car loses during the contract and you hand it back at the end. Buying is usually better if you drive very high mileages, plan to keep the car for many years, or want to own an asset you can sell later, because lease contracts charge for excess miles and leave you with nothing to sell. The Corolla’s strong resale value makes both routes attractive, so the right choice depends on your annual mileage, how long you keep cars, and whether you value ownership or flexibility more.
What happens at the end of a Toyota Corolla lease?
At the end of a Toyota Corolla lease you normally return the car to the leasing company or dealer, where it is inspected for damage beyond fair wear and tear and for excess mileage, and any charges are billed to you. In the United States, a disposition fee of around 350 dollars is commonly charged at lease end, and you may also have the option to buy the car for its agreed residual value if your contract allows it. In the United Kingdom, personal contract hire agreements simply end with the car being collected, and you can then start a new lease on a newer Corolla. Book the inspection in good time, repair minor damage beforehand, and keep the service history complete to reduce the risk of extra charges.